
Economics is not generally considered one of the “hard” sciences, like physics; assumptions are almost always oversimplified, and theories are difficult to test because you can’t run multiple controlled experiments with identical starting conditions. You also can’t avoid the human element, and if you study economics long enough, you’ll find significant overlap with psychology and sociology. For these reasons, it’s not often that an economic theory gets put to the test in a clear and straightforward way. But the Covid-19 pandemic and the US government response was about as close as you’ll ever get to a real-world test of Modern Monetary Theory (MMT), a somewhat fringe economic theory that began gaining popularity about a decade ago. Looking back three years since the experiment, how did MMT perform?
Let’s define Modern Monetary Theory in case you’re not familiar. MMT is an attempt to explain how government finances work and it makes several bold claims, including:
- Sovereign nations like the United States, Australia, the UK, and Japan, that issue and borrow in their own currencies can never actually “run out of money.” They always have the ability to create more money to fund whatever priorities the government chooses.
- Tax revenues do not actually “fund” the government. Rather, taxes are collected to drain liquidity from the economy and keep a lid on inflation, and to favor or disfavor certain constituents and public policies.
- Government deficits are necessary and, overall, a net positive to society. MMT suggests that you should think of government deficits as public surpluses. A direct consequence of this belief is that a balanced government budget is a counterproductive goal and should not be pursued.
- The ability of sovereign governments to spend money is not unlimited, but the true constraint is inflation, not tax revenue or budget deficits. This means that the analogy of government finances being similar to a household budget is flawed.
The implications of this theory are profound. If true, this would mean, for example, that concerns over Social Security and Medicare going bankrupt are misguided. It also means that the government can always meet its obligations, no matter how large, including entitlement programs, foreign aid, and interest payments on Treasury bonds. It would also suggest that Vice President Dick Cheney was correct when he stated in 2002 that “deficits don’t matter” and that high levels of debt and deficits are not as serious a problem as many people believe (as long as inflation remains under control.)
Before we grade MMT as a theory, it is important to note that MMT contains elements that are both descriptive (as in how the world really works) and prescriptive (as in what policymakers should do in order to maximize economic welfare). Even if we sympathize with one, we may still disagree with the other. In other words, even if we accept that MMT is an accurate description of how government finances work, it does not necessarily follow that policymakers should abandon all fiscal restraint.
Now to the test. In March of 2020, the United States faced a historic triple threat from the Covid-19 pandemic; a public health crisis, a market crisis, and an economic/unemployment crisis. Descending quickly into a deep economic recession, the US government took a page right out of the MMT playbook, implemented “wartime finance,” and borrowed and spent a combined $5 trillion (25% of US GDP) in a brief 12-month period. The Federal Reserve stepped in and ensured that this new borrowing would be financed at very low rates of interest. Concerns about ultimately paying for these emergency spending packages were minimized and shelved for a later date.
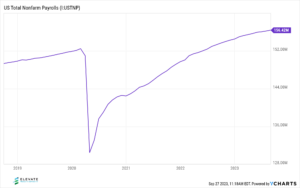
So how did MMT perform when put to the test? I’ll give it a mixed grade overall. The stock market did recover quickly from pandemic lows (in about 6 months) and the recession turned out to be very brief. GDP growth rebounded strongly in the third quarter of 2020 and has remained relatively robust since then. The job market took longer to heal but had recovered all of the jobs that were lost during the pandemic by July of 2022. Personal savings rates soared during this period, and mass evictions and personal bankruptcies were largely avoided.
However, inflation became a significant problem in 2022 and has not yet returned to the benign levels of pre-pandemic America. The Federal Reserve was forced to reverse their accommodative policy very abruptly; their aggressive interest rate hikes in the past 18 months have destabilized markets to some extent and adds to the risk of a recession in the near term. And the national debt grew sharply in the past three years and now rivals the highest levels relative to GDP since the immediate aftermath of World War II. With 20/20 hindsight, it seems that we may have reached the limit to how much the government can borrow and spend in a short period without inflationary consequences and thus what an MMT-inspired policy can achieve.
Sources: https://www.chicagotribune.com/news/ct-xpm-2004-01-12-0401120168-story.html
The Deficit Myth (Stephanie Kelton, 2020)
https://ycharts.com/