
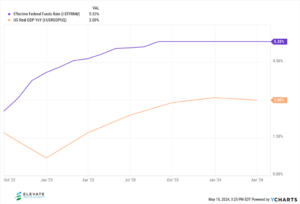
For the past several quarters, economic growth in the US has continued to surprise to the upside. While the economy tends to expand in most years, many analysts had assumed that growth would falter last year in the face of rapidly rising interest rates. In fact, by the end of 2022, the consensus view on Wall Street was that these higher interest rates would likely trigger a recession within 12 months. Instead, the much anticipated “recession of 2023” never came to pass. In fact, GDP growth accelerated throughout the year, showing once again how difficult it is to make forecasts about the markets and the economy.
The concerns about the possibility of an imminent recession weren’t unreasonable; higher rates had helped trigger twin recessions in 1980 and 1982, and the economy in 2022 had become accustomed to ultra-low interest rates for over a dozen years. This led to a lot of pessimism about how the economy could tolerate more “normal” rate conditions. But despite an interest rate shock of more than 5% in just 18 months, the economy has so far persevered.
What happened? With the benefit of hindsight, it is a little easier to understand the resiliency of the economy in the face of sharply higher interest rates. Among the potential reasons are:
- Fixed rate debt – Mortgages and auto loans tend to have fixed interest rates, and many homeowners were able to lock in low rates in 2020 and 2021 before they spiked higher. While the “lock-in” effect has chilled home sale activity to some extent, homeowners that refinanced and decided to remain in their homes have been largely unaffected by higher mortgage rates. Many US corporations had similar foresight and issued longer-term fixed-rate debt at favorable rates before they began to increase in 2022.
- YOLO (You Only Live Once) consumer spending – Aided by high savings rates during the pandemic, consumers have since opened their wallets and spent heavily on experiences like travel and restaurant meals, which are running above pre-pandemic trends. Savings rates are now below pre-pandemic levels. It’s difficult for the economy to fall into recession when consumer spending is this strong.
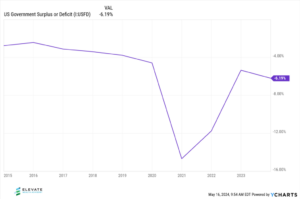
- Federal government deficit spending – The annual US federal budget deficit is currently running above 6% of GDP, which is a level consistent with prior recessions and not expansions. During the Covid pandemic, the US fiscal deficit reached -15% and has since improved substantially. However, the deficit has not fully normalized and is still providing a powerful tailwind to economic growth. Although the Federal Reserve raised interest rates sharply and tightened financial conditions, the government is essentially driving with their feet on the brake and the accelerator at the same time.
- Asset price inflation – Since the lows of March 2020, US stock prices are up 75%, and home values have risen about 40%. For those consumers that own them, the increase in assets values has also helped to drive spending higher. Cash yields above the rate of inflation aren’t hurting, either.
- Long and variable lags – This phrase means the ultimate effects of tighter monetary policy can take several months, or even a year or two, to manifest. It is possible that the economy will slow from here and we just haven’t seen the full effects of higher rates just yet.
In short, financial markets and the economy remain as difficult to forecast as ever. Investors who resisted the temptation to time markets and instead simply stuck to their long-term investment plan in the last couple of years have seen their portfolios grow in value. Time will tell, but perhaps we are just going back to the interest rate environment we had before the Global Financial Crisis. The good news is that markets and the economy appear to have the ability to perform well in a wide variety of different rate environments.